
Global financial markets experienced a severe bout of volatility as a sharp nasdaq tech selloff erased trillions of dollars in market value within a single month. Equity investors across North America, Europe, the Gulf, and emerging markets faced renewed anxiety as major technology stocks led a broad pull-back. High-flying valuations that had fueled market rallies earlier in the year quickly unraveled under the pressure of rising macroeconomic headwinds, shifting monetary policy expectations, and disappointing corporate earnings reports.
The scale of the retreat reflects how heavily global equity indices have become concentrated in a handful of giant technology firms. When these mega-cap market leaders face intense selling pressure, the ripple effects spill over into wider international portfolios. Financial centers in Dubai, Abu Dhabi, Riyadh, and Mumbai felt the sentiment turn cautious, as sovereign funds and retail traders alike re-evaluated their risk exposure to global growth stocks. Understanding the mechanics behind this market shift is essential for anyone navigating international investments today.
Several factors converged to trigger the sudden shift in investor sentiment. Elevated interest rates across major economies have sustained borrowing costs for companies, putting pressure on corporate profit margins. Tech firms, which heavily depend on future cash flow expectations, are particularly sensitive to sustained high borrowing rates. When central banks signal that interest rate cuts may be delayed or proceed more slowly than previously priced in, equity markets naturally reprice growth stocks lower.
The Core Drivers Behind the Nasdaq Tech Selloff
Earnings performance has also played a pivotal role in the recent downturn. While many leading technology corporations continue to generate substantial revenues, investor expectations had reached exceptionally high levels. Any failure to beat quarterly revenue projections, or even cautious forward guidance issued by corporate executives, was met with aggressive profit-taking. Reports from trading desks indicated that institutional capital moved quickly out of high-valuation growth assets and into cash, sovereign debt, or traditional defensive sectors like utilities and healthcare.
Geopolitical tensions and broader macroeconomic uncertainty further eroded market confidence during the period. Rising energy costs, supply chain realignments, and currency fluctuations added layers of complexity for global enterprise operations. As market participants grew concerned about the durability of global consumer demand, the appetite for speculative technology plays and leveraged equity positions diminished rapidly.
For international investors based in the UAE and the broader region, the equity pull-back provides a critical lesson in portfolio construction. Many regional wealth management strategies heavily weight global equity funds dominated by Western technology leaders. When a sudden correction occurs in these concentrated indices, wealth managers must reassess asset allocation balances. Diversification across asset classes, including fixed income, real estate, and regional equities, becomes vital to buffer against sharp equity drawdowns. Readers should note that this analysis provides general financial commentary rather than individualized investment advice.
Who Is Affected and How Portfolios Adapt
Institutional investors, such as pension funds and sovereign wealth entities, often view major equity drops through a long-term lens. For these large market players, market pull-backs can present selective buying opportunities to acquire quality businesses at discounted valuations. However, retail investors and shorter-term traders face immediate capital losses and heightened margin call risks when volatility spikes. The sudden loss of equity value highlights the importance of maintaining strong liquidity reserves to navigate periods of prolonged market stress.
Technology startups and venture capital ecosystems are also indirectly impacted by public equity downturns. When public market valuations for established technology leaders fall, private market valuations tend to follow with a slight delay. Fundraising environments become tighter, and prospective initial public offerings are often postponed until market conditions stabilize. Founder teams across South Asia, the Middle East, and Africa must adjust their cash burn rates and focus on clear paths to profitability rather than rapid scale at any cost.
Looking ahead, market analysts will be closely monitoring upcoming economic indicators to gauge the future path of global stock markets. Central bank policy decisions will remain the primary driver of market liquidity and investor risk appetite. If inflation data continues to cool, central banks may eventually offer relief through monetary easing, which has historically provided strong support for technology sector valuations.
Additionally, corporate earnings trends over the coming quarters will determine whether current market prices accurately reflect fundamental business values. Investors should watch corporate commentary on capital expenditure plans, artificial intelligence monetization strategies, and global demand trends. While market volatility can be uncomfortable, history shows that periodic market corrections are a natural feature of healthy capital markets, helping to clear excess speculative leverage and establish more sustainable long-term valuations.
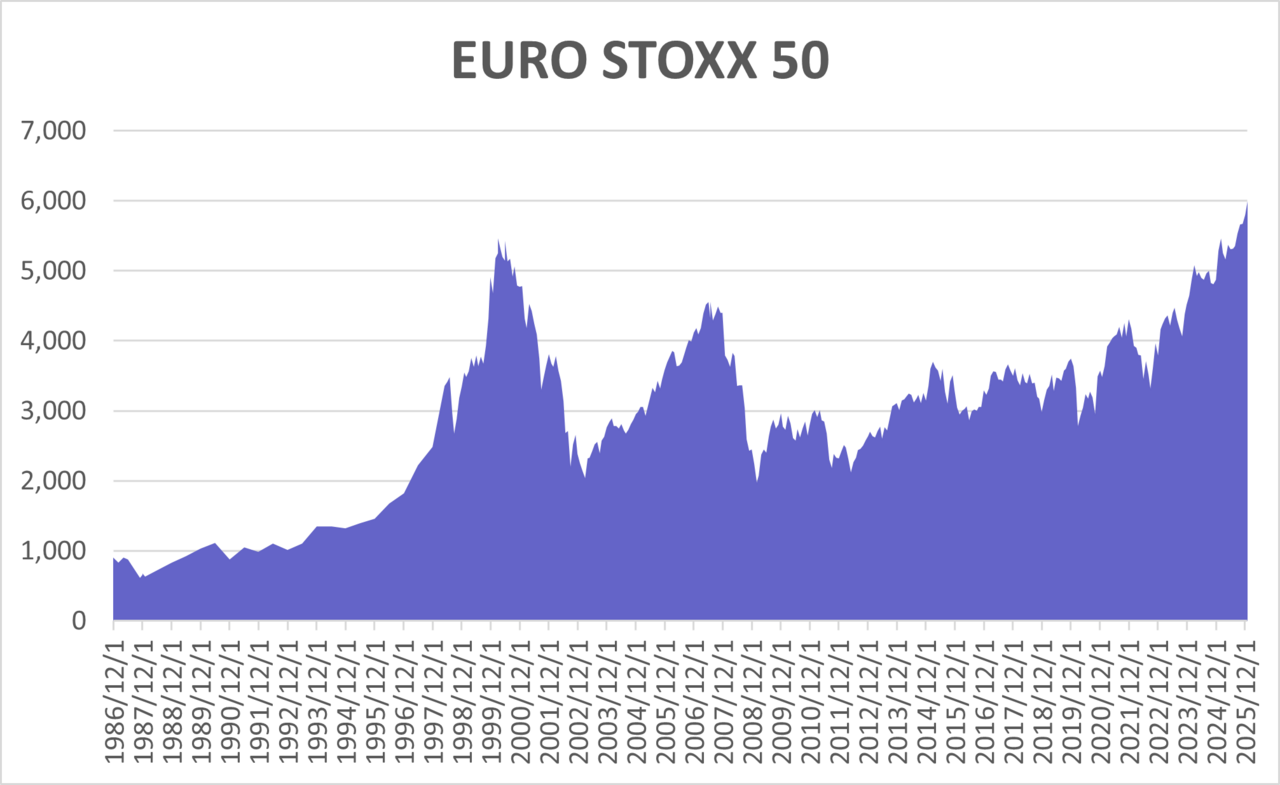
Image: Wikimedia Commons (public domain)
