
The relationship between emerging economies and the U.S. Federal Reserve has long been a focal point for global financial stability. In recent months, observers have noted a subtle but significant shift: emerging markets appear to be less resistant to the Fed’s policy moves than they were in previous years. This trend has implications for currency markets, investor sentiment, and the broader economic outlook across the Gulf, South Asia and Africa.
Emerging Markets Fed Stance: How Banks Are Adapting
At the heart of the change is a growing recognition among emerging-market central banks that maintaining credibility on monetary policy outweighs the temptation to chase short-term growth through loose rates. The Fed’s tightening cycle, driven by high inflation in the United States, has prompted many of these economies to adopt firmer stances rather than opposing the policy shift outright. Consequently, the usual friction, where emerging markets feel pressured to keep rates low to support domestic growth, has eased.
Historically, as the U.S. raised rates, emerging markets often counter-acted by keeping policy rates low, hoping to attract capital and stimulate export demand. This dynamic created volatility in currency markets and strained local banks. New data suggests that several emerging economies now align their policy trajectory more closely with global rates, reducing the likelihood of sudden currency swings. For example, several Gulf Cooperation Council (GCC) countries have adjusted their monetary policy frameworks to better reflect the global risk environment.
One reason for the shift is the increased integration of global financial markets. The rise of cross-border investment flows and the proliferation of global bonds have made it easier for emerging-market economies to benefit from higher global rates without a steep domestic cost. Additionally, the availability of foreign exchange reserves has grown in many countries, allowing central banks to buffer against external shocks without resorting to aggressive rate cuts.
Another factor is the heightened awareness of inflation risks. With the Fed’s policy tightening aimed at curbing inflation, emerging markets now see the dangers of unchecked price rises in their own economies. Consequently, many central banks have adopted a more hawkish stance, even if it means tolerating slower growth in the short term. This approach reflects a shift from a purely growth-driven policy to one that balances growth with price stability.
For investors, the reduced hostility towards the Fed is a double-edged sword. On one hand, it can lead to more stable currency markets and lower borrowing costs for multinational companies. On the other hand, it may mean that emerging-market bonds become less attractive as their yields converge with those of developed markets. Portfolio managers will need to reassess risk-return profiles and focus on sectors that can thrive under tighter monetary conditions.
Policymakers in the Gulf, South Asia and Africa should watch how these changes affect domestic consumption and investment. Countries that have traditionally relied on low rates to spur growth may need to diversify their economic engines. A balanced approach, combining fiscal stimulus with structural reforms, will be key to sustaining growth without compromising monetary credibility.
In practical terms, the trend suggests that emerging-market banks are likely to adopt more disciplined risk management practices. This could include tightening lending standards, improving liquidity buffers, and increasing transparency in their policy communications. Such measures will help maintain confidence among international investors and reduce the likelihood of sudden capital outflows.
Looking ahead, the Fed’s policy path will remain a critical variable. Should the Federal Reserve signal a more rapid tightening, emerging markets may still keep pace, but the window for divergence will narrow. Conversely, if the Fed eases policy, emerging economies will have more room to adjust without risking misalignment. Investors and policymakers alike should monitor Fed minutes, inflation data and global capital flows to anticipate potential shifts.
In conclusion, the evolving dynamic between emerging markets and the Fed reflects a maturation of global financial cooperation. While the economies are no longer as hostile to U.S. policy moves, they must balance this alignment with domestic priorities. The resulting changes in currency stability, bond yields and banking practices will shape the investment landscape for the coming years.
Readers are reminded that this information is general in nature and not tailored financial advice.
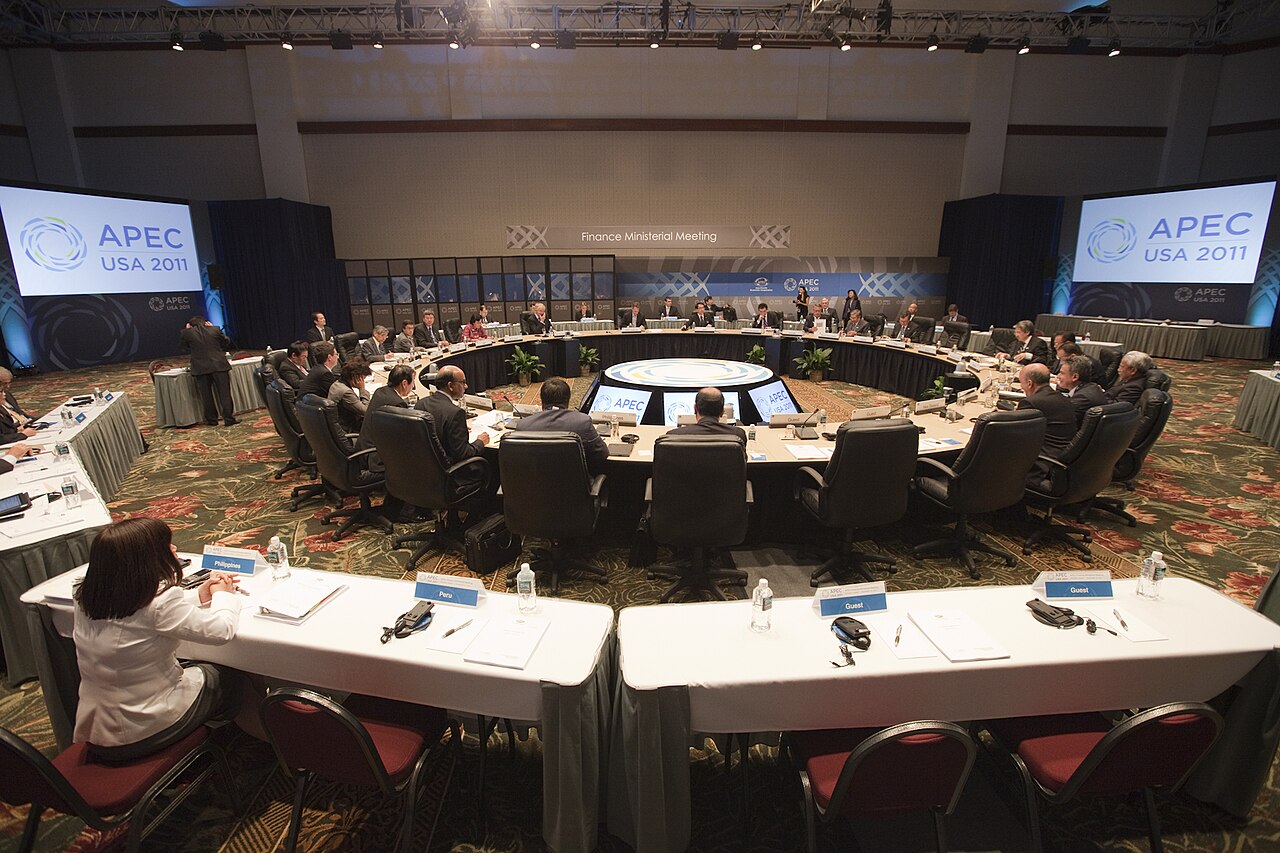
Image: Wikimedia Commons (public domain)
