
Quick answer: Deciding between physical gold vs gold ETF comes down to whether you want physical metal in hand or quick stock market access. Physical gold offers direct ownership of real coins or bars, but it requires secure storage space and dealer markup fees. A gold ETF tracks real bullion spot prices on stock exchanges with lower upfront costs and fast liquidity, though you rely on fund managers to hold the metal.
What is the main difference between physical gold vs gold ETF?
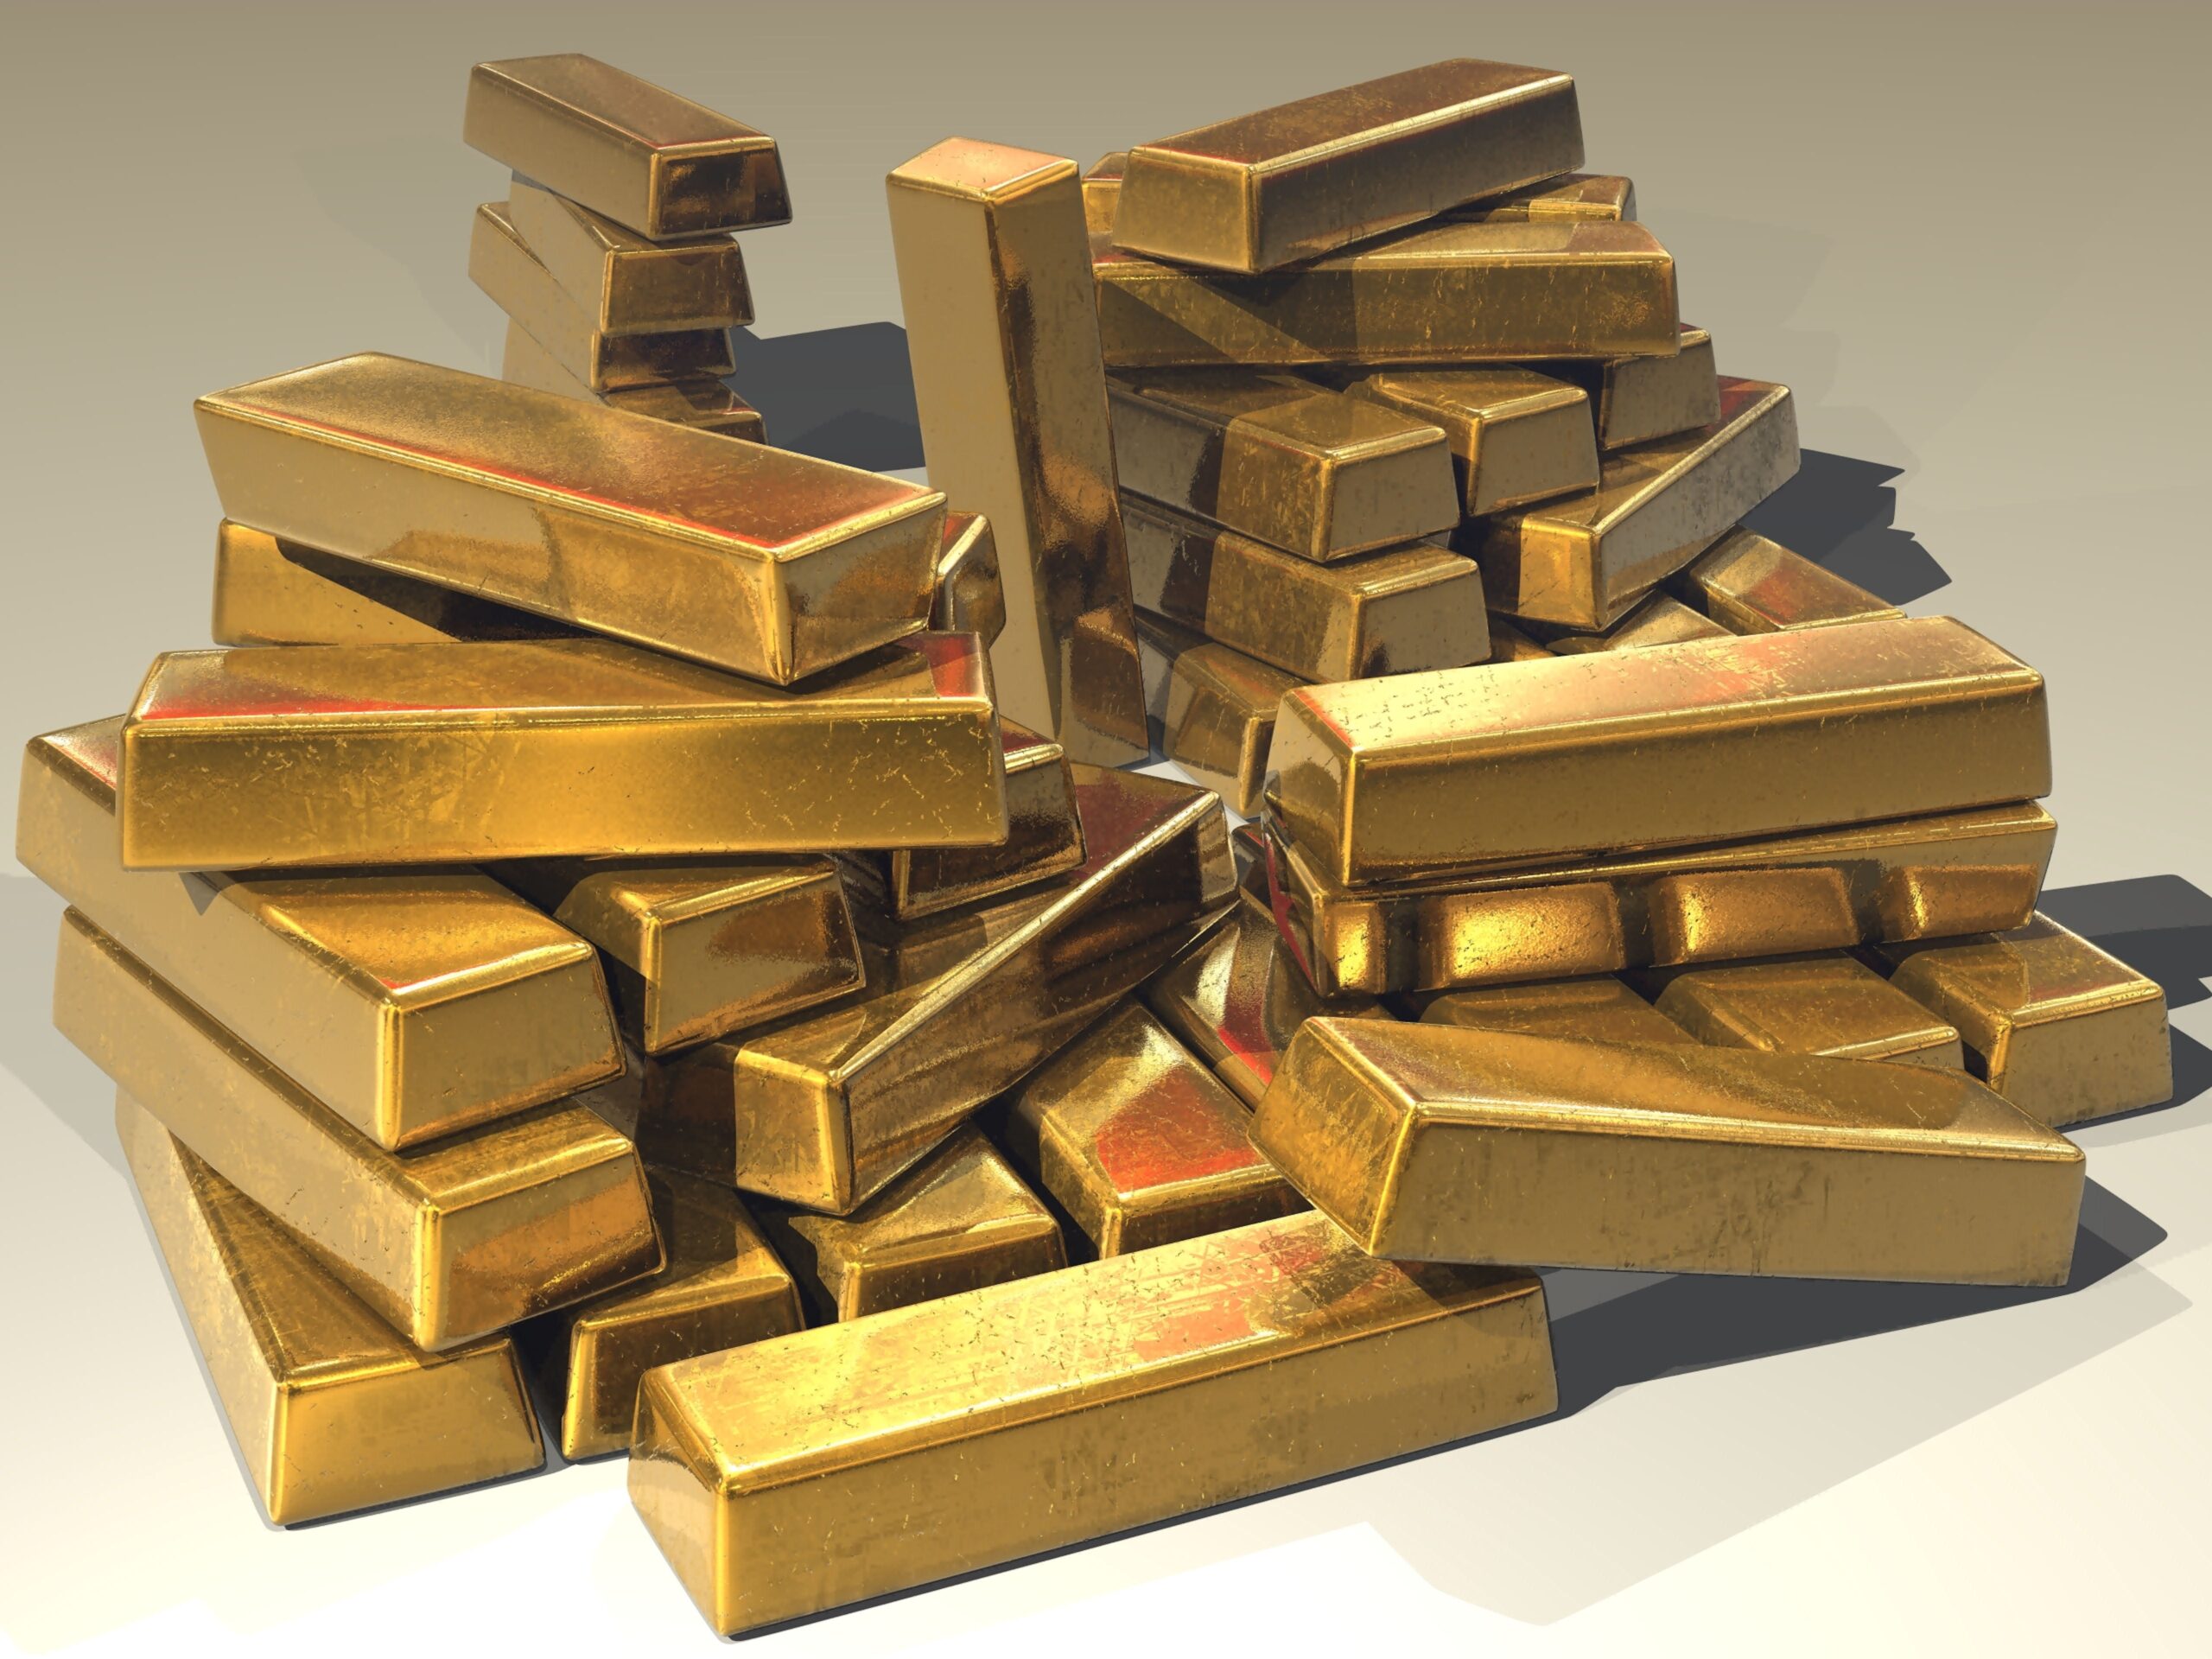
Physical gold means owning real metal in the form of coins, minted bars, or bullion. You purchase these products from trusted precious metal dealers, government mints, or certified coin shops. You hold full legal title to the physical asset, so your asset value does not depend on any bank, broker, or financial exchange.
A gold exchange traded fund (ETF) operates as an exchange-listed security inside a brokerage account. You buy shares in a regulated trust that owns physical bullion stored in secure vaults. Purchasing ETF shares gives you direct exposure to gold market prices without taking personal custody of heavy metal bars.
Buying physical coins or bars requires paying dealer markups above spot market prices. These premiums cover manufacturing costs, minting, transport, and dealer profit margins. When you track global gold price trends, you will see that physical purchases carry wider buying and selling spreads than fund shares.
Gold ETFs eliminate high upfront dealer markups and physical shipping fees. Instead, fund managers deduct an annual management fee, known as an expense ratio, from the fund assets. Popular physical gold funds typically charge between 0.15% and 0.40% each year, which gradually reduces long-term fund returns.
How to compare storage, liquidity, and safety risks
Storage requirements create the largest operational difference between these two assets. Physical gold demands a safe storage plan, such as a fireproof home safe or a bank safety deposit box. You must also purchase private property insurance to protect your investment against home burglary, fire, or accidental damage.
Gold ETFs remove personal storage duties and insurance costs completely. Fund custodians keep heavy bullion bars inside vault networks located in major financial centers around the world. Regular independent audits verify that vault reserves match total investor fund shares exactly.
Liquidity measures how quickly you can convert an investment back into cash. You can buy or sell gold ETF shares instantly during stock market trading hours with a single click. Your broker settles the trade quickly, allowing you to transfer funds to your bank account within standard settlement windows.
Selling physical bullion takes more time, planning, and effort. You must visit a physical dealer or ship your metal to a certified buyer for inspection and testing. Dealers test metal purity before giving a final cash quote, which can take several business days to settle.
Counterparty risk also sets these choices apart. Physical gold carries zero counterparty risk because your possession remains secure even during financial crisis periods. Gold ETFs carry minor counterparty risk because you rely on fund trustees, vault custodians, and stock brokerages to operate correctly.
What are the tax rules for gold investments?
Tax rules significantly affect your net returns when you sell gold investments for a profit. Many buyers assume gold ETFs enjoy standard stock capital gains tax rates, but federal tax guidelines classify them differently.
According to the IRS, physical bullion coins and physically backed gold ETFs are classified as collectibles when held in taxable accounts. Holding either asset for longer than one year triggers a maximum long-term capital gains tax rate of 28%. You can verify these regulations directly through the official IRS capital gains tax guidance page.
Short-term profits on gold held for 12 months or less face standard income tax rates. This rule applies equally to physical gold coins, minted bars, and physically backed fund shares in taxable brokerage accounts.
You can reduce annual tax friction by holding gold assets inside tax-advantaged accounts like a Roth IRA. Using retirement accounts shelters your investment gains from collectible tax rules during your asset building years. Beginners who want low starting costs can also examine fractional digital gold entry options to build metal exposure with small starting balances.
Physical gold vs gold ETF comparison table
This side-by-side comparison breaks down the core operational differences between holding tangible metal and purchasing exchange-traded fund shares.
| Feature | Physical Gold | Gold ETF |
|---|---|---|
| Asset Ownership | Direct physical possession of coins or bars | Fractional ownership of fund trust shares |
| Upfront Cost | 2% to 10% dealer markup over spot price | Tight bid-ask spread plus broker commission |
| Ongoing Expenses | Home safe costs, vault rent, private insurance | 0.15% to 0.40% annual fund expense ratio |
| Liquidity Speed | Slower: requires dealer visit or physical shipping | Immediate: trade instantly during market hours |
| Counterparty Risk | Zero risk: direct physical metal ownership | Minor risk: reliance on fund custodian stability |
| US Tax Category | Taxed as collectible (up to 28% long-term) | Taxed as collectible (up to 28% in taxable accounts) |
Who should choose physical gold and who should choose a gold ETF?
Choosing the right format depends on your financial timeline, budget, and personal security priorities. Both assets act as inflation hedges, but they serve distinct investor roles.
You should choose physical gold if you prioritize self-reliance and privacy. Tangible metal suits long-term wealth preservers who want assets independent of electronic networks or corporate custodians. It is ideal for people planning to hold generational wealth or pass physical assets directly to heirs.
You should choose a gold ETF if you want flexibility, low overhead, and simple portfolio tracking. Fund shares suit active investors who like to rebalance assets easily across stock and bond accounts. It is ideal for individuals who want low transaction friction without managing physical home security.
Before purchasing either asset option, review your overall asset mix and evaluate key features:
- Physical coins offer complete privacy and direct physical control during systemic market disruptions.
- Gold ETFs provide instant liquidity and simple integration inside tax-advantaged retirement accounts.
- Dealer markups reduce initial physical returns, while annual ETF fees compound gradually over time.
- Storage security demands careful home safe setup or vault rental planning for physical metal holdings.
Frequently asked questions
Can I exchange my gold ETF shares for physical gold?
Most retail gold ETFs do not allow individual investors to exchange shares for physical bullion coins or bars. Only authorized institutional participants trading massive share blocks can redeem shares directly for underlying metal.
Are gold ETFs taxed differently than physical gold in the US?
In taxable brokerage accounts, the IRS taxes both physical gold and physically backed gold ETFs as collectibles. Long-term capital gains on both assets face a maximum federal tax rate of 28%.
Does a gold ETF track the spot price of gold exactly?
A gold ETF tracks the spot price of gold very closely, but minor price differences can occur. Annual management fees and small tracking differences cause fund share prices to deviate slightly from live spot metal rates over time.
What is the main cost advantage of a gold ETF over physical gold?
Gold ETFs eliminate upfront dealer markups and recurring home safe or vault storage fees. Investors pay low annual fund expense ratios and tight trading spreads instead of physical minting and shipping premiums.
This article provides general information only and does not constitute financial, legal, or investment advice.
