
When international investment institutions revise their long term gold price target, global financial markets take notice. Central banks, wealth managers, and retail investors across the Gulf region and emerging markets closely monitor these adjustments to gauge the future health of the global economy. Recent market shifts have prompted major Wall Street analysts to recalibrate their multi year projections for precious metals, balancing short term headwinds against powerful structural tailwinds.
Understanding how global institutions calculate a gold price target requires looking at several interlocking financial variables. Sovereign buying patterns, real interest rates, currency movements, and geopolitical stability all play pivotal roles in determining whether bullion trends upward or experiences periodic corrections. While near term fluctuations can create volatility, long term targets typically focus on the underlying macroeconomic forces that govern precious metals over decades.
Key Drivers Behind Revisions to the Gold Price Target
Investment banks regularly update their economic models to reflect changing macroeconomic realities. The primary catalyst for adjusting any metal forecast is the trajectory of central bank interest rates. When benchmark rates remain elevated, holding non yielding assets like bullion carries an opportunity cost. However, as central banks signal potential rate cuts or shifts toward monetary easing, the fundamental appeal of precious metals tends to strengthen, driving analysts to project eventual market rebounds.
Another major factor influencing these projections is the persistent demand from official sovereign reserves. Over recent years, central banks across developing economies and the Middle East have accumulated record quantities of bullion to diversify their foreign exchange holdings away from dominant fiat currencies. This steady structural demand creates a resilient floor under the market, preventing deeper drawdowns even during periods of temporary strength in global bond yields.
Exchange traded fund flows also serve as a crucial barometer for institutional sentiment. When institutional capital returns to metal funds following periods of outflows, price momentum often accelerates rapidly. Analysts incorporate these fund flows alongside physical retail demand in key Asian markets to establish realistic long term valuation bands for precious metals.
Impact on Gulf Investors and Emerging Markets
For investors in the UAE, the wider Gulf Cooperation Council, and South Asia, shifts in metal forecasts carry significant practical implications. In these regions, physical gold is not merely a speculative asset but a core component of generational wealth preservation and cultural commerce. Local retail markets often react swiftly to international price signals, influencing trading volumes across major bullion hubs like Dubai.
Wealth managers across the region frequently use these institutional forecasts to advise clients on portfolio allocation strategies. During periods of economic uncertainty or inflationary pressure, a modest allocation to precious metals is widely viewed as a traditional hedge. Keep in mind that this analysis is for general informational purposes only and does not constitute personalized financial advice.
Regional sovereign wealth funds and corporate treasuries also evaluate long term metal projections when structuring their asset portfolios. By tracking global forecast revisions, institutional buyers in the Gulf can better time their strategic entry points, ensuring that their alternative asset allocations align with broader international macroeconomic cycles.
Navigating Market Rebounds and Future Volatility
Market cycles in precious metals are rarely linear, and price target adjustments often account for intermediate periods of consolidation before a broader recovery takes hold. Short term profit taking, fluctuations in foreign exchange rates, and sudden shifts in market risk sentiment can cause temporary price pullbacks. However, historical trends suggest that sustained macroeconomic shifts remain the ultimate driver of multi year bullion rallies.
Investors evaluating these institutional targets should look beyond the headline numbers and focus on the underlying assumptions. Factors such as persistent government debt burdens, ongoing currency debasement worries, and structural supply constraints in the mining sector frequently underpin optimistic long term outlooks. When major financial institutions project a future rebound, it often reflects an expectation that these structural support factors will eventually reassert themselves over cyclical pressures.
What to Watch in the Global Metals Market
Moving forward, market participants should closely monitor monthly policy statements from major central banks to assess the timing of global monetary shifts. Any unexpected changes in interest rate guidance will likely trigger immediate reactions across currency and commodity markets. Additionally, tracking quarterly reports on central bank gold purchases will provide clear visibility into whether sovereign demand remains robust enough to support long term target revisions.
Physical demand metrics from key importing nations across Asia and the Middle East will also offer valuable clues regarding price elasticity. If physical buyers continue to absorb market pullbacks, the foundation for a sustained market recovery will remain intact. Ultimately, keeping a disciplined perspective on macro trends will help investors navigate both temporary dips and long term advances in global bullion markets.
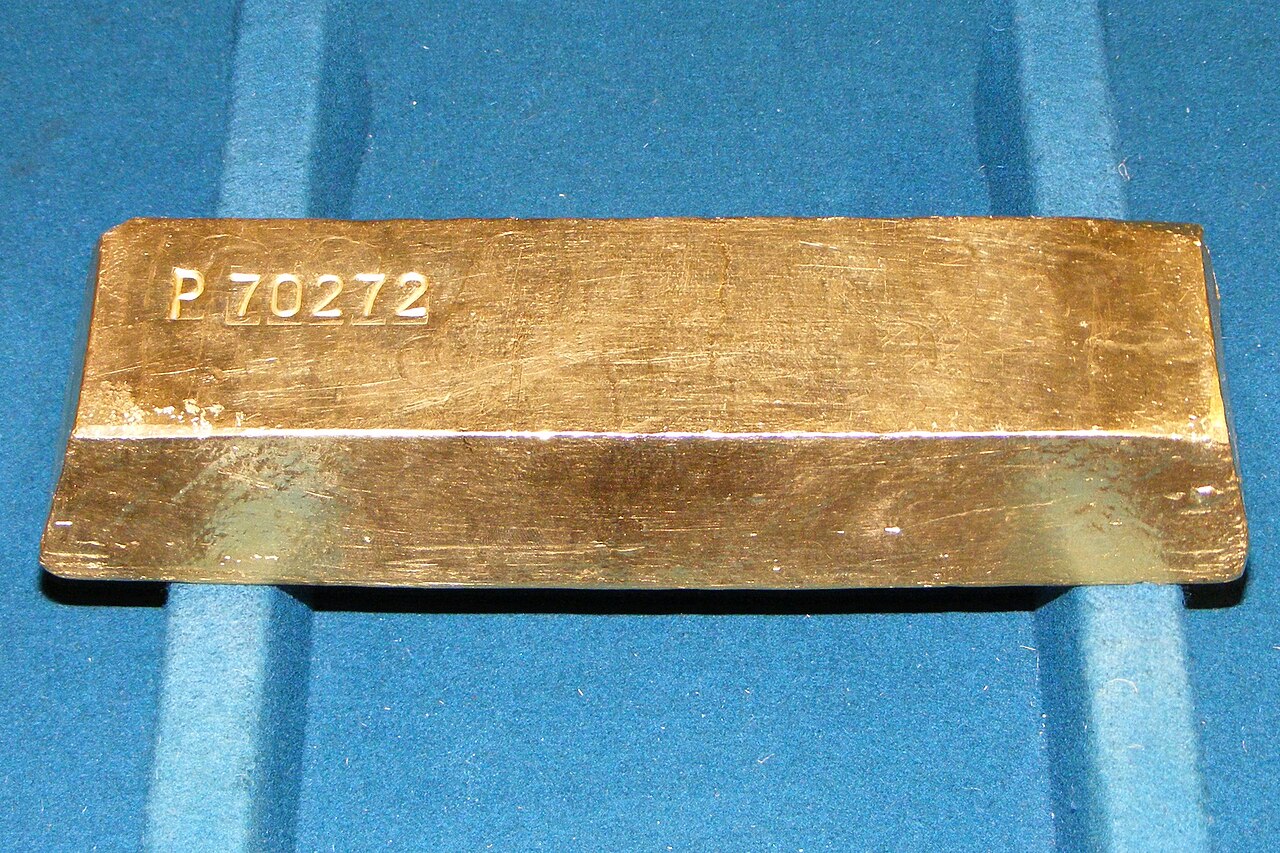
Image: Wikimedia Commons (public domain)
