
Investors across global markets are closely tracking the latest gold sachs gold price forecast as central bank decisions continue to reshape expectations for precious metals. Recent updates from major investment banks indicate that prolonged high interest rates in the United States are placing downward pressure on gold values. When central banks maintain a firm stance against inflation, yield-bearing assets become more attractive compared to non-yielding commodities. This dynamic has prompted prominent research teams to recalibrate their medium-term projections for bullion prices.
Understanding the underlying drivers of these market recalibrations requires examining how monetary policy influences commodity trading. When central bank officials signal that interest rate cuts may be delayed or smaller than previously expected, the opportunity cost of holding physical gold rises. Investors seeking regular income often shift their capital into government bonds or treasury bills that offer dependable returns. Consequently, institutional demand for bullion can moderate, leading analysts to lower their price targets for upcoming quarters.
Evaluating the Factors Behind the Gold Sachs Gold Price Forecast
The primary catalyst for revising precious metals projections stems from changing expectations surrounding central bank interest rate trajectories. Economic data showing persistent inflation or resilient employment numbers often forces monetary authorities to maintain elevated borrowing costs for longer periods. As a result, market analysts must adjust their baseline assumptions regarding currency strength and investor appetite. A robust U.S. dollar typically makes dollar-denominated commodities more expensive for overseas buyers, further dampening international purchases.
Beyond interest rates, institutional capital flows play a decisive role in shaping commodity valuations. Exchange-traded funds backed by physical gold often experience capital outflows during periods of aggressive monetary tightening. When retail and institutional investors redeem their holdings in these funds, large quantities of metal return to the open market, creating additional supply pressure. Analysts carefully monitor these fund movements when adjusting their long-term commodity models.
It is important to remember that general market commentary and commodity projections provide macro insights rather than personal financial advice. Individual portfolio decisions should always reflect personal risk tolerance and specific investment goals.
Impact on Sovereign Buyers and Central Bank Reserves
While private investor demand may soften during periods of high interest rates, official sector buying presents a contrasting dynamic. Sovereign entities and central banks, particularly across emerging economies, have spent recent years accumulating physical reserves to diversify away from foreign currency holdings. This structural buying helps establish a soft floor under commodity valuations even when commercial financial institutions reduce their targets. Analysts balance these opposing forces when publishing revised estimates.
In regions such as the Middle East and South Asia, physical demand for gold remains closely tied to traditional retail practices, seasonal festivities, and long-term wealth preservation. Higher local prices can temporarily cool retail purchases, but physical ownership remains a cornerstone of household savings across these markets. Consequently, local bullion dealers pay close attention to international research updates to manage their inventory risks effectively.
How Global Economic Conditions Influence Metals Demand
Geopolitical uncertainty also acts as a primary counterweight to high interest rates in the global gold market. During periods of heightened international tension or financial sector fragility, investors frequently seek the perceived safety of tangible assets. This safe-haven demand can quickly reverse downward price trends, creating sudden rallies that challenge pessimistic wall street predictions. Analysts must continuously weigh geopolitical developments against prevailing macroeconomic metrics.
Furthermore, broader inflationary trends play a complex role in commodity valuation. While high interest rates tend to suppress gold prices, persistent inflation erodes the real purchasing power of fiat currencies, maintaining the appeal of physical bullion over multi-year horizons. Financial institutions must constantly calibrate how these competing forces influence both immediate price movements and extended market trends.
What Investors Should Monitor in Coming Months
Looking ahead, market participants should closely follow upcoming announcements from monetary policy committees for clear signals regarding future rate trajectories. Any unexpected economic cooling or shifts in policy tone could prompt renewed interest in non-yielding assets. Investors should also monitor economic data releases, including consumer price indexes and labor market reports, as these indicators directly influence central bank strategies.
In summary, while recent bank research reflects a more cautious near-term outlook for gold due to persistent interest rate pressures, the broader market remains sensitive to multiple structural drivers. Tracking institutional forecasts alongside global macroeconomic shifts will remain essential for anyone evaluating wealth strategies in the current financial environment.
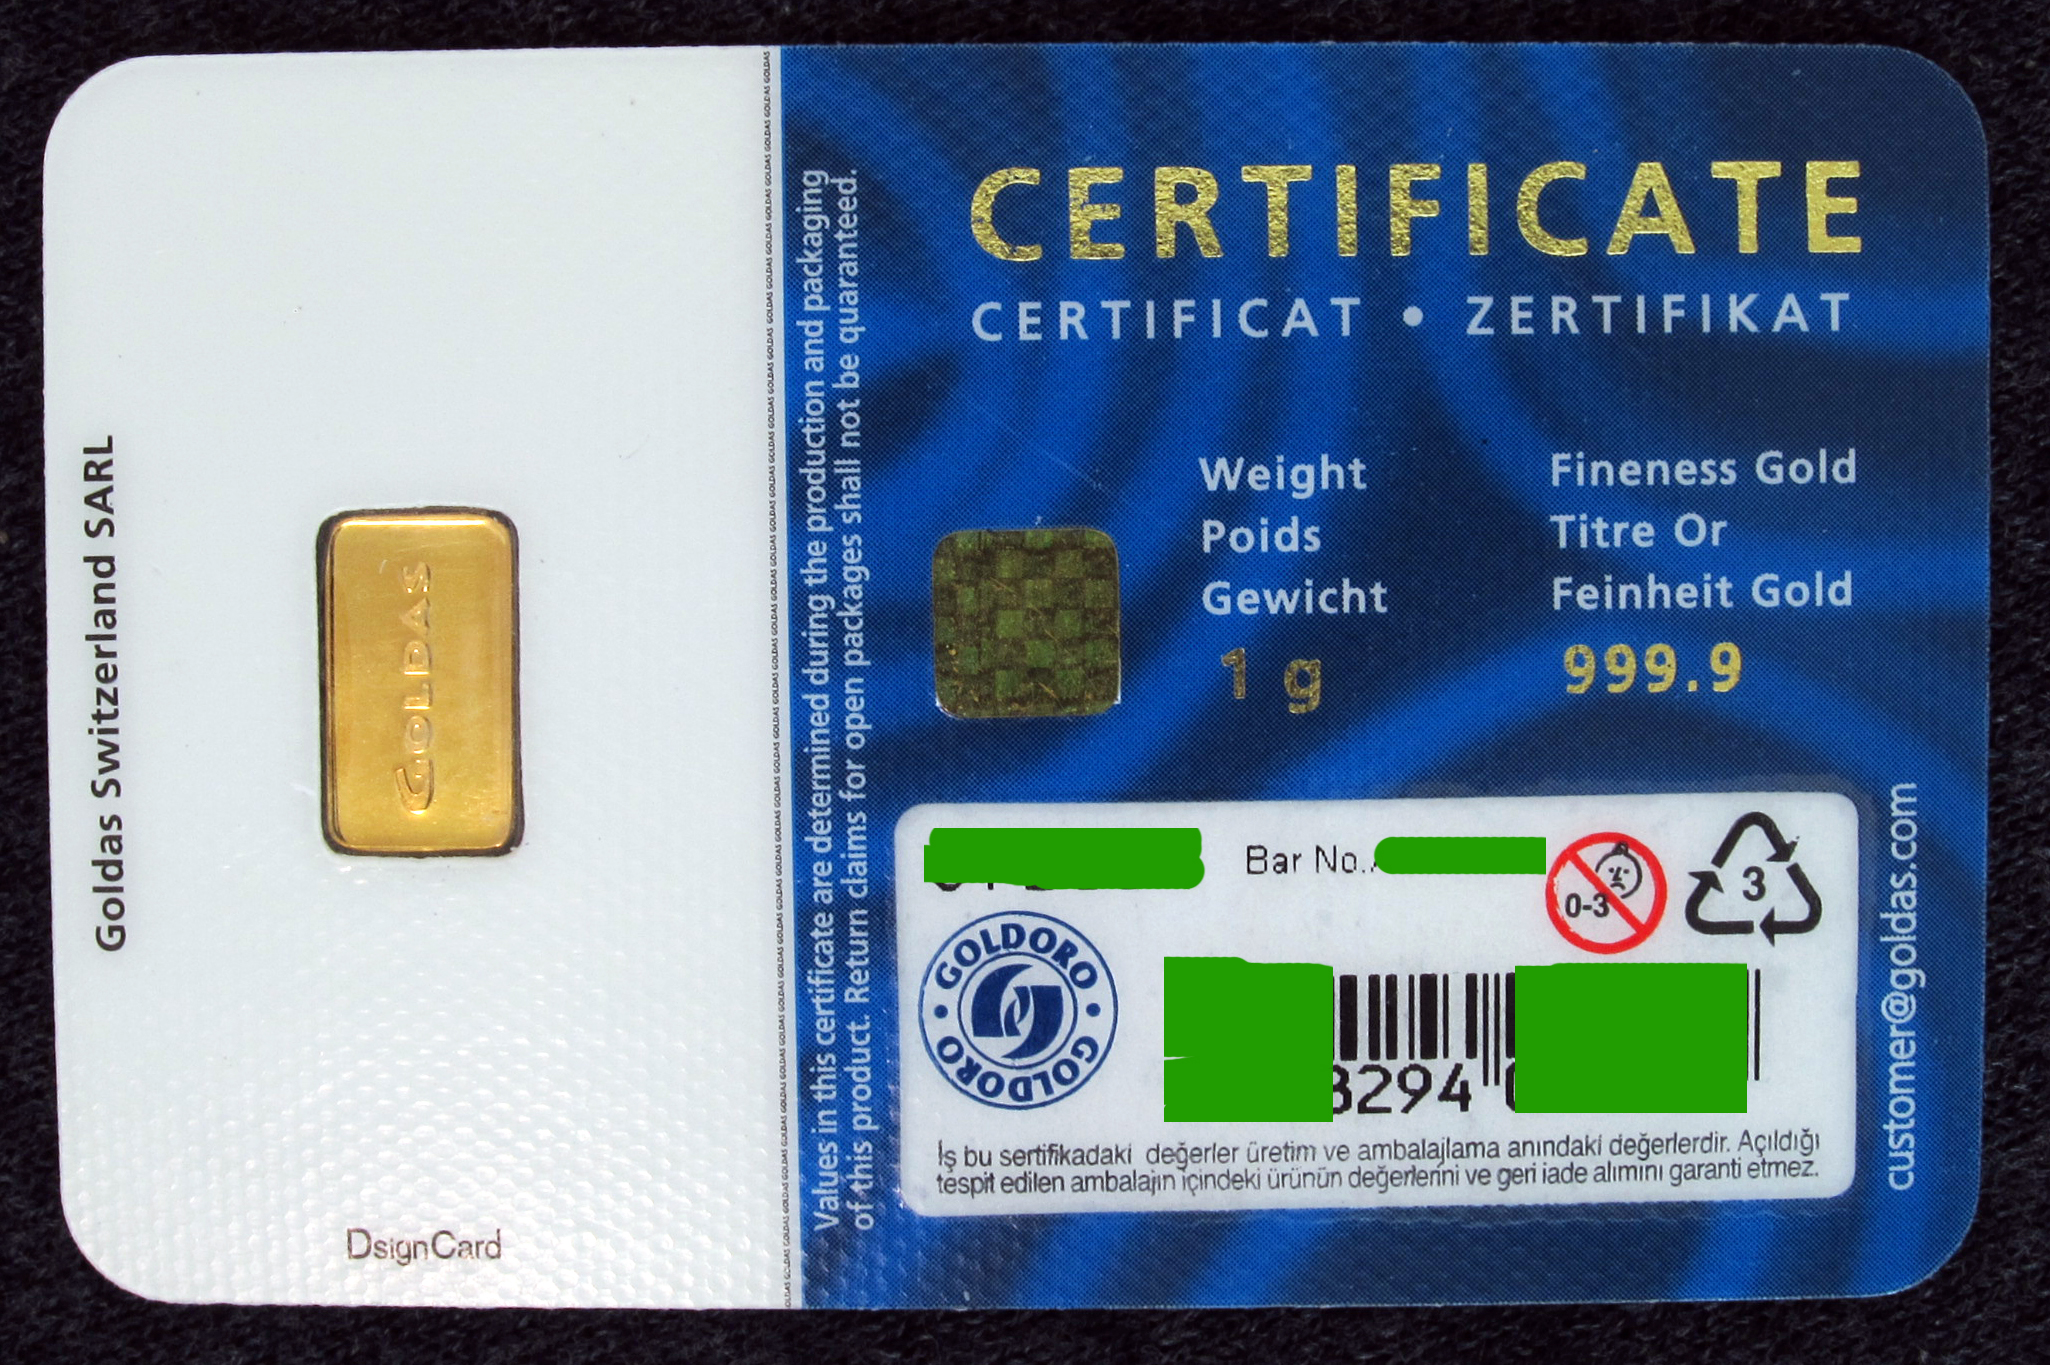
Image: Openverse (public domain)
