
When more American households and institutions buy Treasury bonds, the American government’s cost of borrowing can rise. This trend, growing domestic ownership of U.S. debt, has been a quiet driver of higher interest rates in recent years, according to analysts who track the Treasury market. The phenomenon is subtle but important for investors, mortgage holders and businesses that depend on cheap credit.
How Domestic Buying Shapes Treasury Yields
U.S. Treasury bonds are sold in auctions that attract a broad mix of buyers: foreign central banks, pension funds, insurance companies and private investors. When a larger share of the new issues is purchased by domestic entities, the government receives less foreign capital. Since foreign investors often accept lower yields in exchange for the safety and liquidity of U.S. debt, a shift toward domestic buyers can force the Treasury to offer higher rates to attract enough bids. In effect, domestic ownership of U.S. debt feeds directly into the price-yield relationship that determines borrowing costs.
Over the past decade, domestic holding of Treasury securities has climbed from roughly 40 percent to more than 55 percent of the total market. This rise is partly due to the retirement of large pension funds that had previously leaned heavily on foreign reserves, and to the growing appetite of U.S. banks for safe assets. Each time the Treasury issues a new bond, the domestic demand for that debt grows, tightening the supply of low-yield opportunities and nudging rates upward.
When Treasury yields climb, the ripple effects spread across the financial system. Mortgage rates, credit card interest, and the cost of corporate borrowing all tend to move in tandem with Treasury yields. A modest 10-basis-point increase in the 10-year Treasury yield can translate into a similar rise for adjustable-rate mortgages and a few basis points higher for corporate bond spreads.
For the broader economy, higher borrowing costs can cool consumer spending and dampen business investment. Conversely, savers who rely on fixed-income securities may see their returns improve. The balance between these forces determines whether the economy experiences modest growth or a slowdown.
Financial advisers often point out that while rising Treasury yields can signal a tightening of fiscal conditions, they are also a reflection of investor confidence. When domestic investors are willing to buy more U.S. debt at higher yields, it suggests a robust appetite for safe assets, which can be reassuring during periods of global uncertainty.
In the Gulf region, where many investors hold U.S. Treasury bonds as part of diversified portfolios, the shift toward domestic ownership in the U.S. can mean higher yields on the bonds they hold. This may affect the return on debt-financed projects and the cost of refinancing for companies that rely on U.S. dollar borrowing.
What should investors watch? First, Treasury auction results that indicate the share of domestic buyers. Second, the Federal Reserve’s policy stance, as it directly influences short-term rates and expectations for future yield curves. Third, the performance of large domestic holders such as pension funds, which can shift the demand balance overnight.
To navigate these changes, investors can diversify into other fixed-income instruments, such as corporate bonds with higher credit spreads, or consider inflation-protected securities that offer better protection against rising rates. Those with mortgages should review their loan terms and consider refinancing if the spread between mortgage rates and Treasury yields widens significantly.
In summary, the growing domestic ownership of U.S. debt is quietly nudging interest rates higher, with broad implications for borrowing costs, investment returns, and economic growth. Understanding this trend helps investors and borrowers anticipate changes and adapt their strategies accordingly. This is general information and not financial advice.
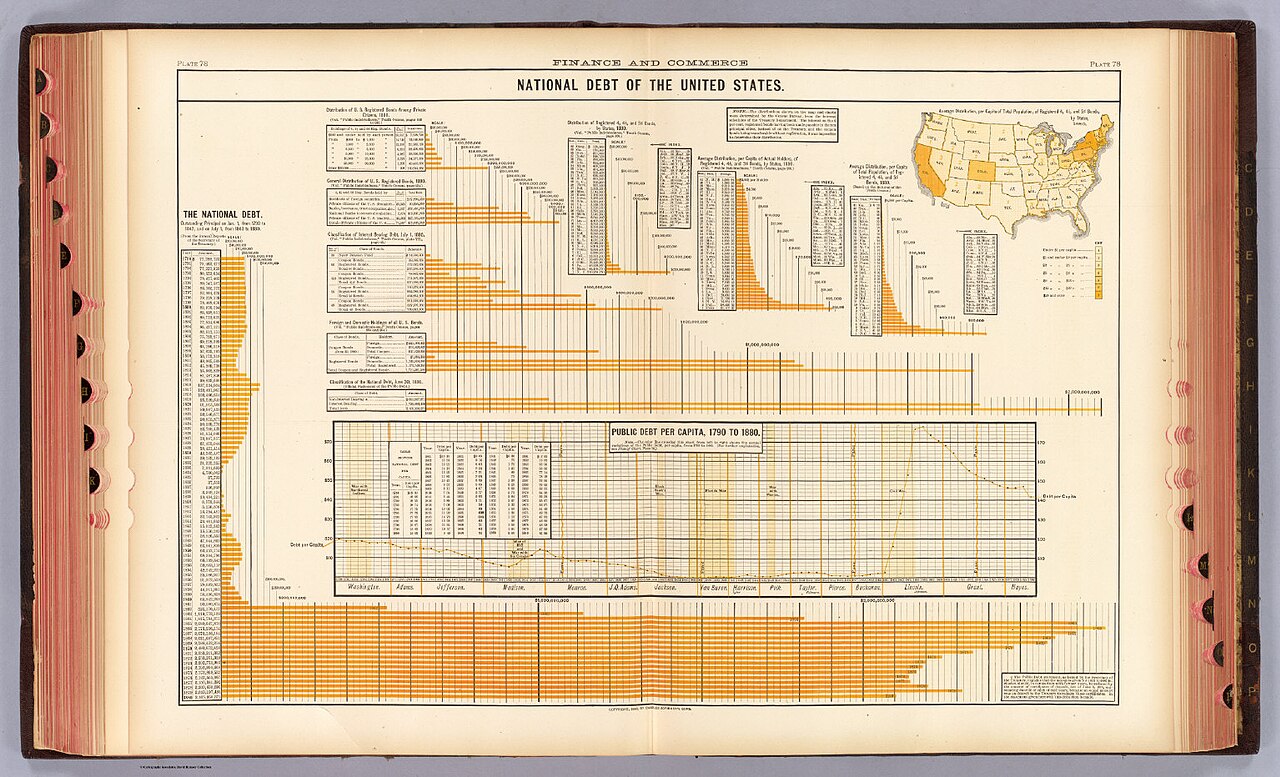
Image: Wikimedia Commons (public domain)
